Earning a steady monthly salary of ₹50,000 (an annual package of ₹6.0 to ₹7.5 Lakh) is a major personal and financial milestone in India. Purchasing your first brand-new car or upgrading from a two-wheeler represents enhanced safety, family convenience, and social elevation. However, without disciplined budgeting, car ownership can swiftly turn from a proud asset into an overwhelming financial drain.
The Golden 15%–20% Rule of Auto Financing
Financial planners strongly advise that your total monthly automotive expenditure (loan EMI + fuel + insurance allocation + maintenance) should never exceed 20% to 25% of your net take-home pay. For a ₹50,000 monthly salary, this translates to:
- Maximum Monthly Loan EMI: ₹7,500 to ₹9,000 (15% to 18% of net pay; absolute ceiling of ₹10,000).
- Monthly Fuel Budget: ₹3,000 to ₹4,500 (assuming 600–800 km of city commuting).
- Monthly Maintenance & Insurance Sinking Fund: ₹1,500 to ₹2,000.
- Total Sustainable Monthly Mobility Outflow: Capped at ₹12,000 to ₹15,000.
Exceeding these limits risks choking your emergency savings, mutual fund SIPs, rent/home loan obligations, and discretionary lifestyle spending.
Understanding the 20/4/10 Budgeting Framework
When shopping for a car on a ₹50k income, apply the globally proven 20/4/10 Rule tailored for the Indian automotive market:
- 20% Down Payment: Put down at least 20% to 30% of the on-road price in cash. For a ₹6 Lakh car, this equals a down payment of ₹1.20 to ₹1.50 Lakh. This prevents you from falling into negative equity where you owe the bank more than the depreciated car is worth.
- 4-Year Loan Tenure (Max 5 Years): Restrict your car loan repayment period to 48 to 60 months. Avoid seductive 7-year (84-month) loans; while they lower the monthly EMI, you end up paying massive compounded interest to the bank.
- 10% Total Transportation Cost: Ensure your loan EMI alone remains strictly near 15% (around ₹7,500 to ₹9,000), leaving ample breathing room for fuel and routine maintenance.
What We Love: 4 Key Advantages of Entry-Segment Ownership
Buying a car in the sub-₹7.5 Lakh bracket comes with massive practical advantages that protect your wallet:
- Tiny Depreciation Loss: Entry hatchbacks and micro-SUVs (like Wagon R, Swift, and Alto) hold the highest residual value in India, losing just 30–35% of their value after 4 years compared to 50%+ for luxury cars.
- Class-Dominating Fuel Economy: Modern 1.0L and 1.2L engines achieve 22–26 kmpl in petrol and over 32–34 km/kg in CNG, keeping your monthly fuel bill lower than a typical weekend dining budget.
- Dirt-Cheap Routine Servicing: Standard periodic annual services for Maruti Suzuki, Hyundai, and Tata entry models cost just ₹3,500 to ₹6,000 per year.
- Low Insurance Renewal Premiums: Lower Insured Declared Value (IDV) translates to comprehensive annual insurance renewals costing just ₹12,000 to ₹18,000.
What to Consider: Critical Pitfalls to Avoid on a ₹50k Income
Before signing loan paperwork, guard yourself against these common financial traps:
- Resist the 'Top-Spec Variant' Trap: Top-spec trims inflate prices by ₹2.0 to ₹2.5 Lakh for cosmetic additions like alloy wheels, ambient lighting, and push-button start. Buy a mid-spec trim (like Swift VXi, Tiago XT, or Punch Adventure) and install essential aftermarket accessories later.
- Beware of Zero-Down-Payment Schemes: 100% on-road financing balloons your monthly EMI beyond ₹13,000 and forces you into negative equity for the first 3 years.
- Never Compromise on Insurance Add-ons: Always opt for Zero Depreciation, Engine Protect, and Return to Invoice (RTI) cover in your first 3 years. A major accidental repair bill should never derail your monthly salary.
Realistic Total Cost of Ownership (TCO) Breakdown
Many first-time buyers mistakenly look only at the showroom price tag. Below is the realistic 5-year Total Cost of Ownership for an entry-level car (like a Maruti Alto K10 or Celerio) versus a mid-segment hatchback (like a Tata Tiago or Tata Punch) on a ₹50k salary:
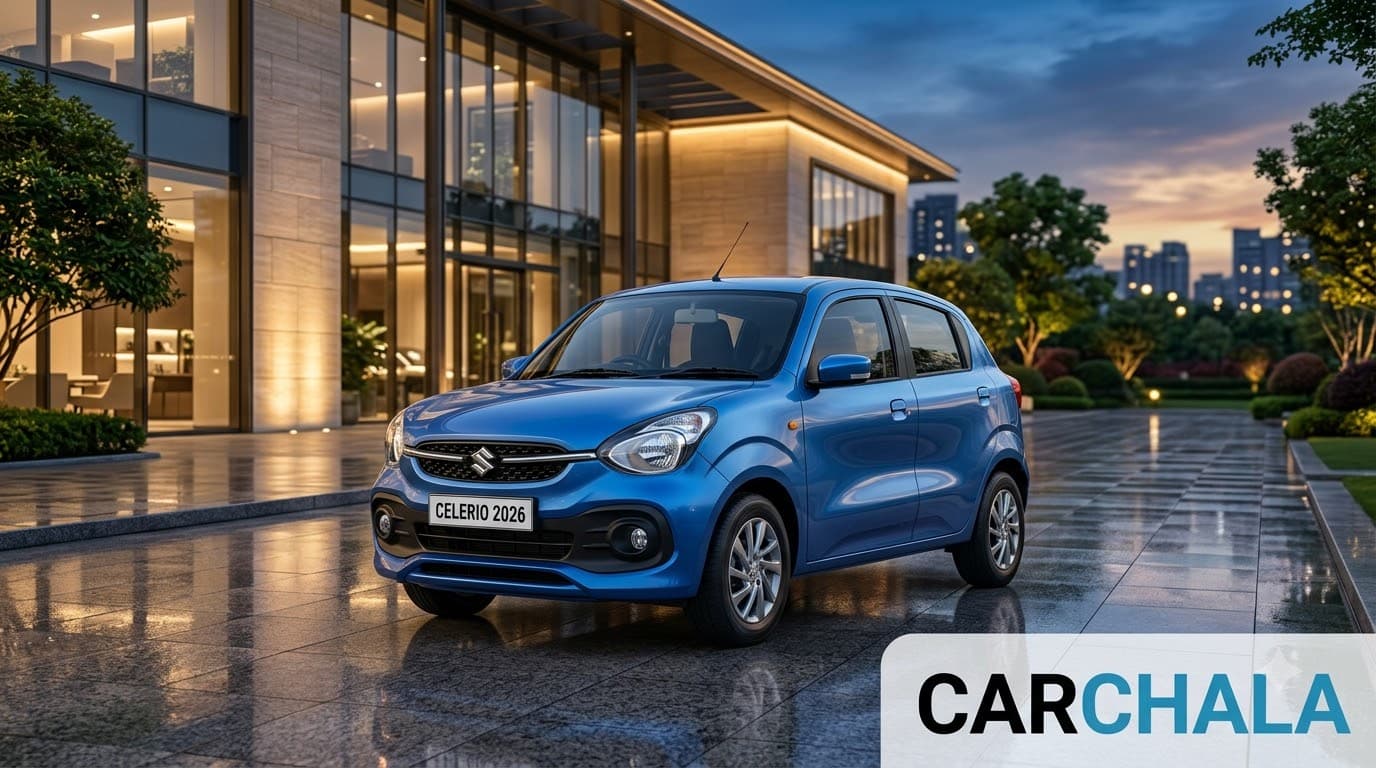
- Entry-Level Option (₹5.5L On-Road): Down payment of ₹1.10L + 5-year loan of ₹4.40L at 9.0% interest = EMI of ~₹9,130/month. Annual service cost = ₹4,000–₹5,000. Comprehensive insurance = ₹16,000/year.
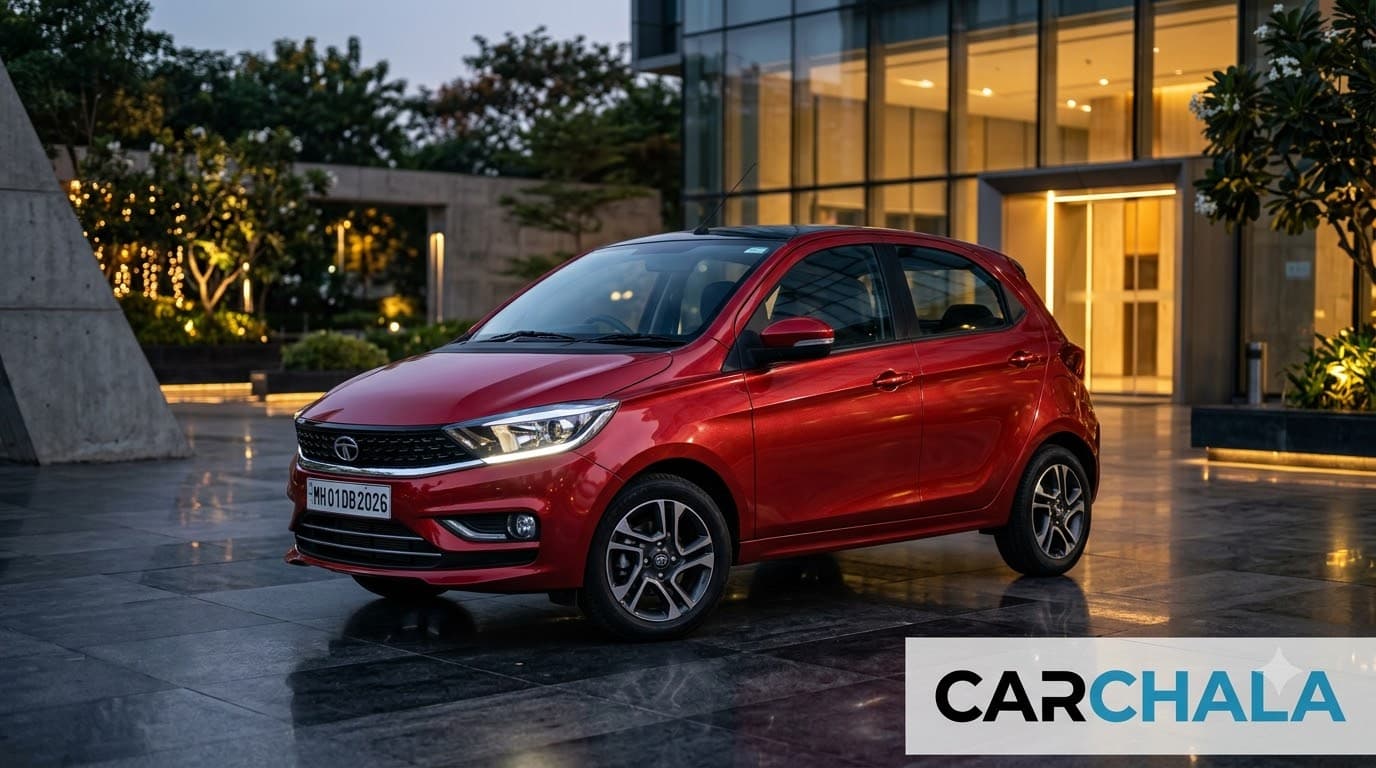
- Mid-Hatchback Stretch (₹7.5L On-Road): Down payment of ₹1.80L + 5-year loan of ₹5.70L at 9.0% interest = EMI of ~₹11,830/month. Annual service cost = ₹6,000–₹7,500. Comprehensive insurance = ₹22,000/year.
Fuel Economics: Petrol vs. CNG Running Cost Matrix
With petrol prices hovering around ₹95 to ₹105 per liter in 2026, fuel efficiency is the single biggest determinant of your monthly cash flow:
- Petrol Car (e.g., Maruti Celerio @ 20 kmpl real-world): Running 1,000 km per month requires 50 liters of petrol, costing roughly ₹5,000/month (₹5.00/km).
- Factory CNG Car (e.g., Wagon R S-CNG @ 28 km/kg real-world): Running 1,000 km per month requires ~36 kg of CNG (at ₹80/kg), costing roughly ₹2,880/month (₹2.88/km).
- Annual Savings with CNG: Approximately ₹25,440 per year, which completely covers your car's annual insurance premium and two routine scheduled services!
Smart Tips for Buying on a ₹50k Salary
- Choose Base or Mid Variants: Opt for a mid-trim (like Swift VXi, Tiago XT, or Punch Adventure) and install aftermarket reverse cameras or seat covers as needed.
- Pre-Close High-Interest Consumer Debt: Before applying for an auto loan, clear off credit card balances or personal loans to boost your CIBIL score above 750. This unlocks prime auto loan interest rates (8.65%–9.0% vs 11%+), saving you thousands in interest over 5 years.
- Maintain an Emergency Sinking Fund: Never use 100% of your bank balance for the down payment. Keep at least 3 months of emergency household expenses intact.